TRIDENTADJUSTING · CONSTRUCTION

// Illinois & Indiana · Storm claims · Roofing · Siding · Gutters

Storm hit your house? Start here.

Trident is a licensed public adjusting firm and a general contractor. We adjust the loss and work the construction, in Illinois and Indiana. One free visit starts both.

  • InspectionFree · about 45 min
  • You getWritten photo report
  • CoverageIllinois + NW Indiana
  • Licensed public adjusters in Illinois and Indiana
  • Our own crews build it, layer by layer, and photograph every stage
  • We never ask you to waive or cover a deductible

Rather talk? Call or text (903) 952-2766

Step 1 of 5Free · about 1 minute
What happened?

Pick the closest one.

No cost, no obligation. We don't sell your information.

01 Two ways in

Have a claim, or just need a roof? Pick your lane.

We adjust the loss and work the construction. Same team, same phone number. What you need decides who shows up first.

Trident Adjusting & Consulting

I have an insurance claim, or think I should.

The insurance company's adjuster works for the insurance company. A public adjuster works for you.

  • We photograph and measure the whole loss, dated and geotagged
  • We read the certified policy and tell you plainly what it owes
  • Line-item estimate, presented to the carrier, every disagreement in writing
  • Underpaid or denied? We reopen and re-present. If they dig in, appraisal under the policy.
Start a free claim review →
Trident Construction Group

I need a roof, siding or gutters. No claim.

Free inspection, written photo report, then a quote with quantities on every line so you can compare it against anyone else's.

  • Full tear-off, decking checked sheet by sheet
  • IKO Cambridge or Dynasty architectural shingles
  • Commercial flat roofs: TPO, EPDM, modified bitumen
  • Metal roofing: standing seam, exposed-fastener panels, metal shingle
  • DaVinci composite slate and shake, cedar, clay and concrete tile, natural slate
  • Siding, soffit, fascia, trim wrap and seamless gutters
Book a free inspection →

02 How it works

From the first photo to the last shingle.

  1. 01STEP 01

    Free visit

    About 45 minutes. Roof, siding, gutters, interior if there's a leak. Everything photographed.

    Day 1
  2. 02STEP 02

    Straight answer

    A written report with photos. If it's a claim, what your policy owes. If nothing needs fixing, we say so.

    Within days
  3. 03STEP 03

    Claim handled

    If there's a claim, Trident Adjusting documents it, presents it, and holds the carrier to its deadlines.

    If you have a claim
  4. 04STEP 04

    Built right

    Trident Construction builds it in eleven layers, in order, with photos of every stage sent to you.

    Build day

03 When the carrier says no

Denied is a position, not a verdict. We don't give up on claims.

Most storm claims that get denied or lowballed were never argued with the right evidence. We build the file the carrier can't wave off, and we keep going until the policy pays what it says.

Not every "no" is a denial

A lot of letters say the damage is covered, then pay $0 because the carrier's number came in under your deductible. That isn't a denial. It's an estimate you can challenge. Send us the letter and we'll read it with you, free.

Send us the letter →

"My insurance denied everything. Trident came out. Yes it took about 2 months but Allstate paid for everything!"

Ivan H. · HomeAdvisor review
  1. 01
    Rebut in writingWe answer the denial line by line, with photos, measurements and the policy language, and put it on the record.
  2. 02
    Re-inspect togetherWe meet the carrier's adjuster on the roof and walk the damage with them, so it's documented by both sides.
  3. 03
    Reopen with new evidenceWeather data, manufacturer specs, code requirements, test squares. A second look with a stronger file.
  4. 04
    Invoke appraisalWhen the carrier won't move, most policies let each side name an appraiser to settle the amount, under the policy's own terms. How it works →
  5. →
    Then we build itThe same photos and measurements become the build plan. One team, first photo to last shingle.

04 When talks stall

Your policy has a tie-breaker. It's called appraisal.

Most homeowner and commercial policies include an appraisal clause. When you and the carrier agree the storm is covered but can't agree on how much, either side can invoke it. Each side names an appraiser, the two appraisers pick an umpire, and any two of the three set the amount. No lawsuit, no courtroom.

Appraisal decides

  • The scope: what has to be replaced, not patched
  • The price of doing it right, with the right materials
  • Items the carrier's estimate left out

Appraisal doesn't decide

  • Whether the loss is covered at all
  • What the policy language means
  • Deadlines and conditions in the policy

We invoke it under your policy's appraisal provision as written, and agree only to the conditions the policy itself sets. And appraisal doesn't stop the build: with written notice and full documentation before tear-off, your roof goes on while the number gets settled.

Ask if your policy has the clause →How disputes get resolvedWe're not attorneys. We read the policy with you and explain what it says in plain English.
Appraisal panelAmount of loss
YOURSYour appraiserIndependent. Chosen by you, paid by you. Inspects and writes the full scope.
UMPIREThe umpirePicked by the two appraisers. Steps in only on what they can't agree on.
THEIRSCarrier's appraiserChosen by the insurance company. Often the same firms that wrote the low estimate.
2 / 3

Two signatures set the amount. The moment any two of the three agree, the number is written down and the carrier pays on it.

  1. 01
    Demand in writingOur letter invokes the clause and names your appraiser. The clock starts.
  2. 02
    Panel formsThe carrier names theirs. The two agree on an umpire.
  3. 03
    Inspect and reconcileBoth appraisers walk the roof. Most of the scope gets agreed line by line.
  4. 04
    AwardTwo of three sign. The carrier issues payment on the award.

Not our client? That's fine.

We also serve as appraiser and umpire for other firms.

Public adjusters, contractors and attorneys bring us the file when the number won't move. Written fee up front, Xactimate scope, panel handled start to finish.

Appraisal services →

05 What you're paying for

A roof is eleven layers. Tap one and watch it go on.

Every layer lands in the order our crews install it. Photos are from our own jobs, so this is the order you should expect on any quote.

Detail A · Roof + wall assembly01 / 11

06 Roof systems we build

Commercial flat roofs to designer tile. Not just shingles.

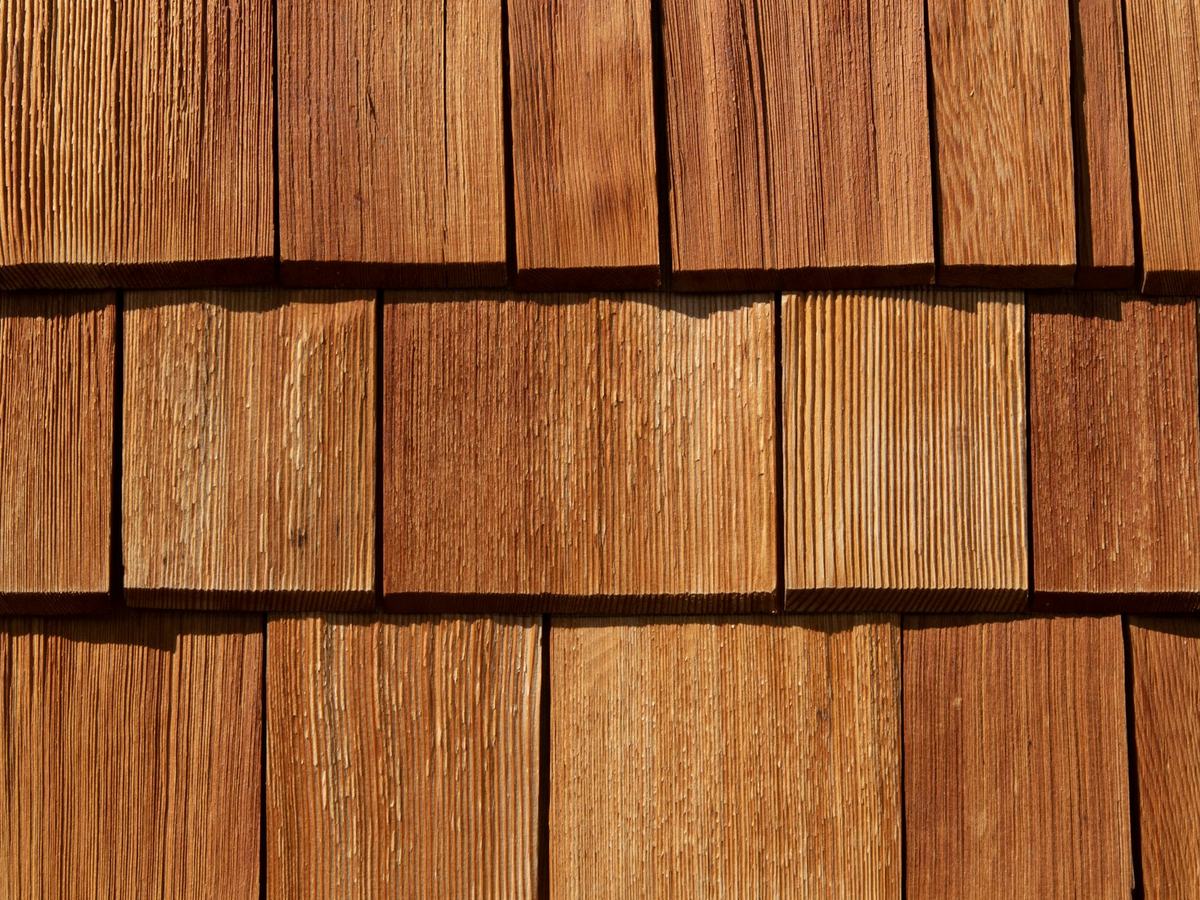
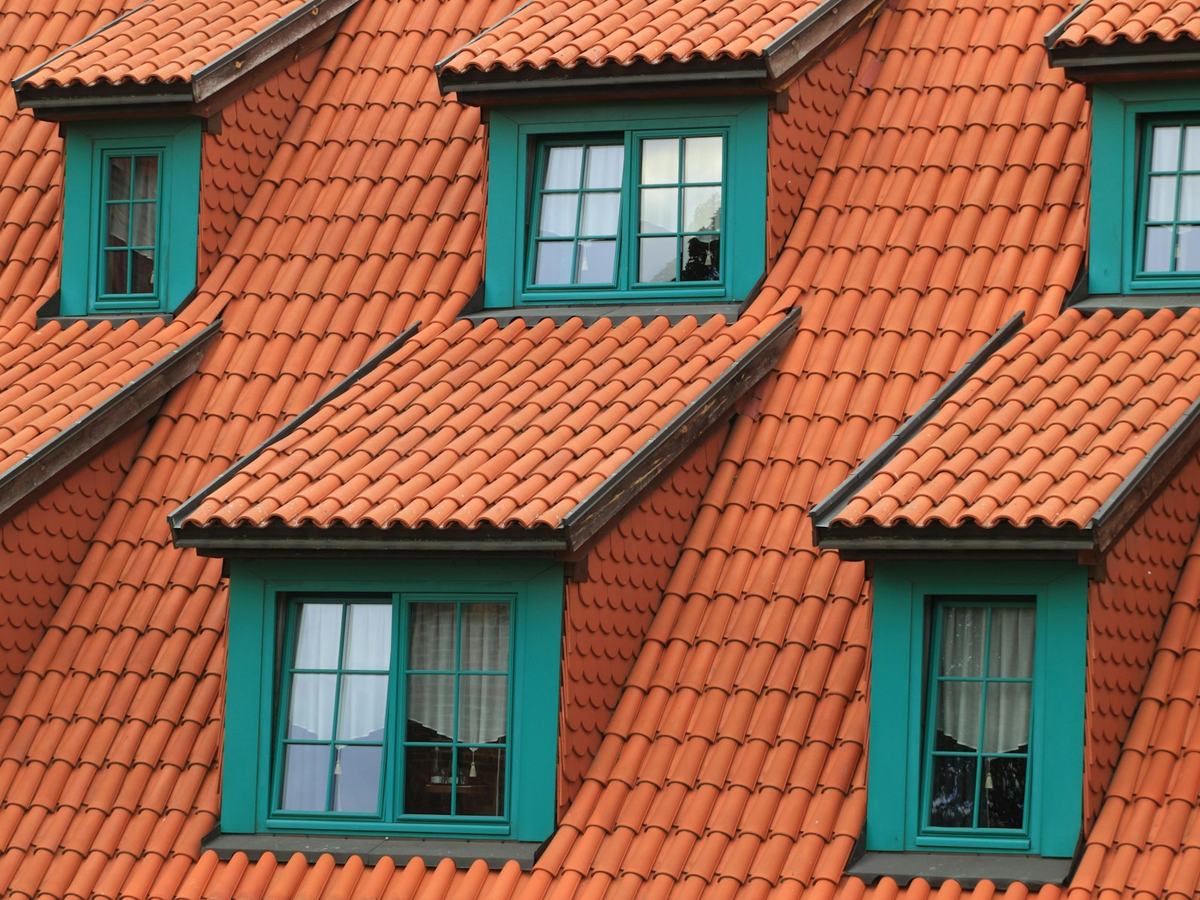
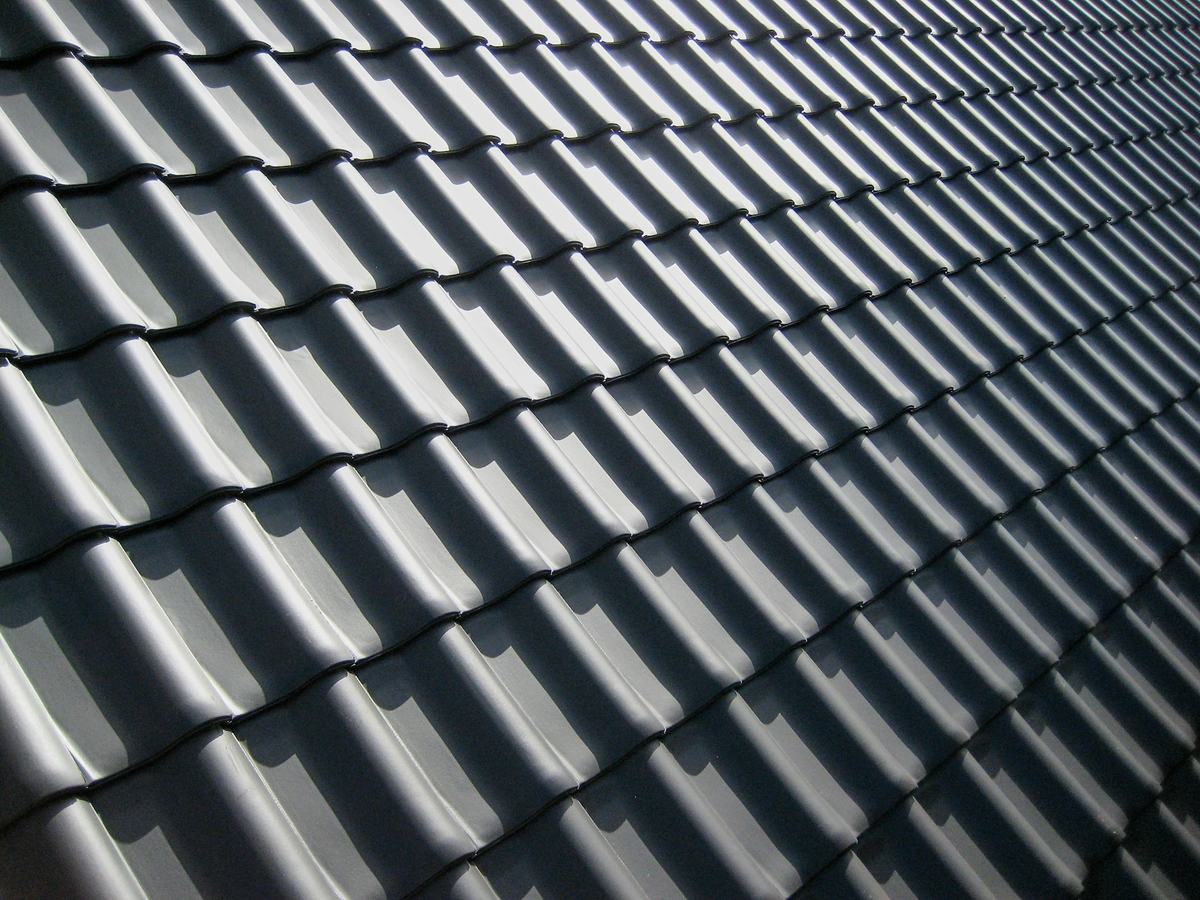
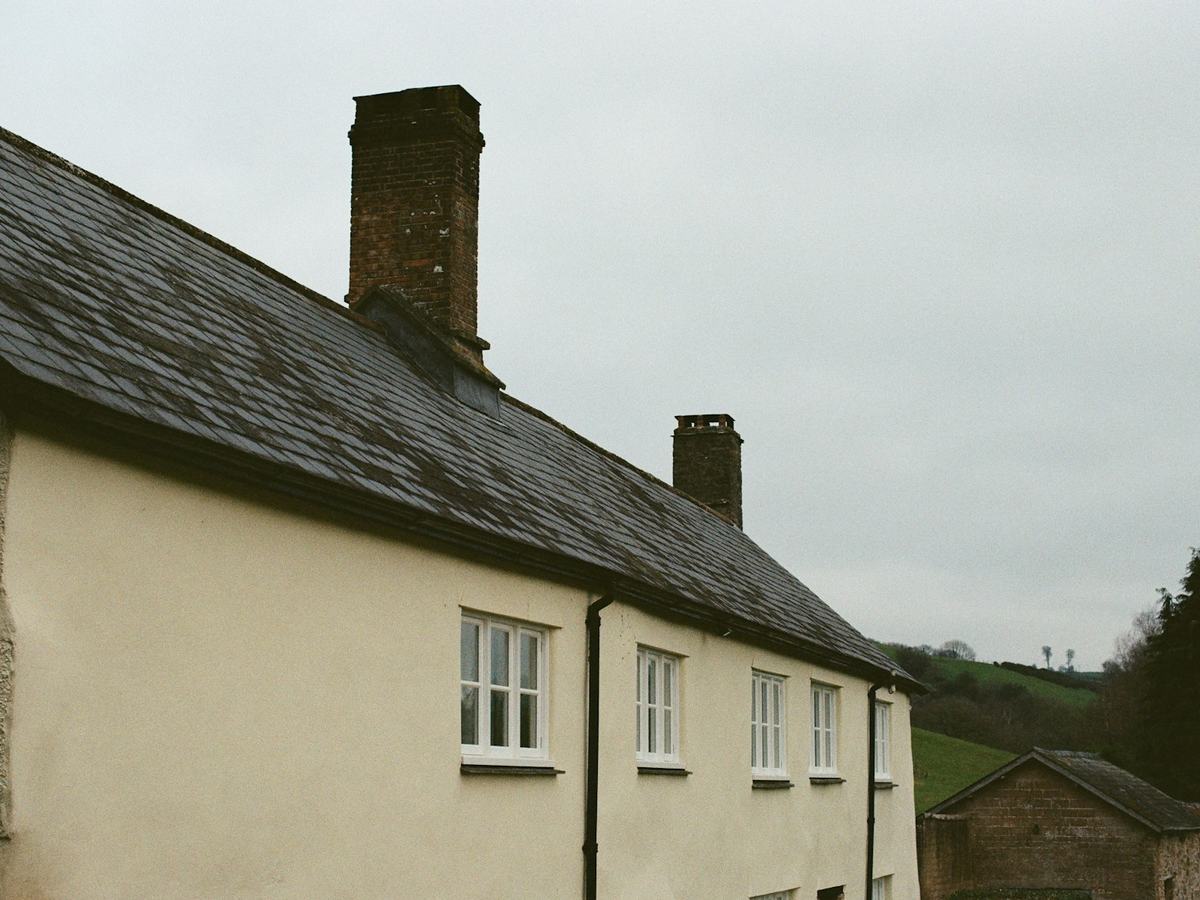
Architectural asphalt is most of what the suburbs need. We also build commercial low-slope roofs, standing-seam and panel metal roofs, DaVinci composite slate and shake, cedar shake, clay and concrete tile, and natural slate. Design references below; Trident jobs are in the next section.

Design references via Unsplash (Unsplash License), except the Trident job noted.

07 Recent work

Recent Trident jobs.

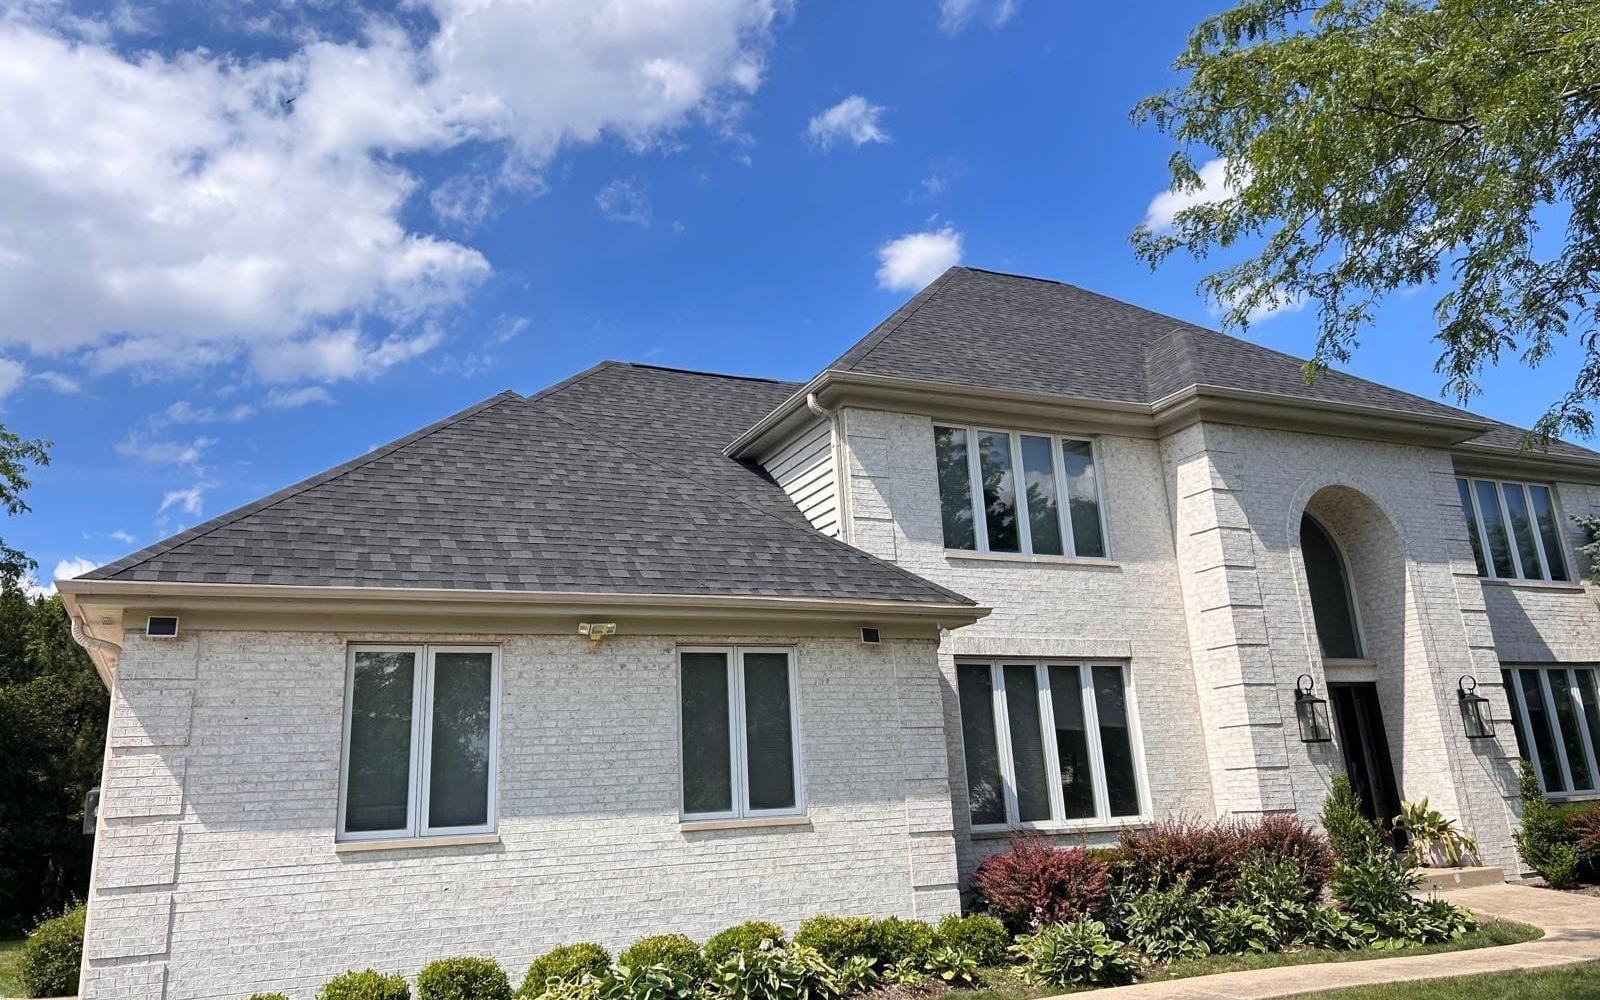
Large white-brick two-story home in Palatine with a new charcoal architectural shingle roof
Trident job · Palatine, IL · Roof
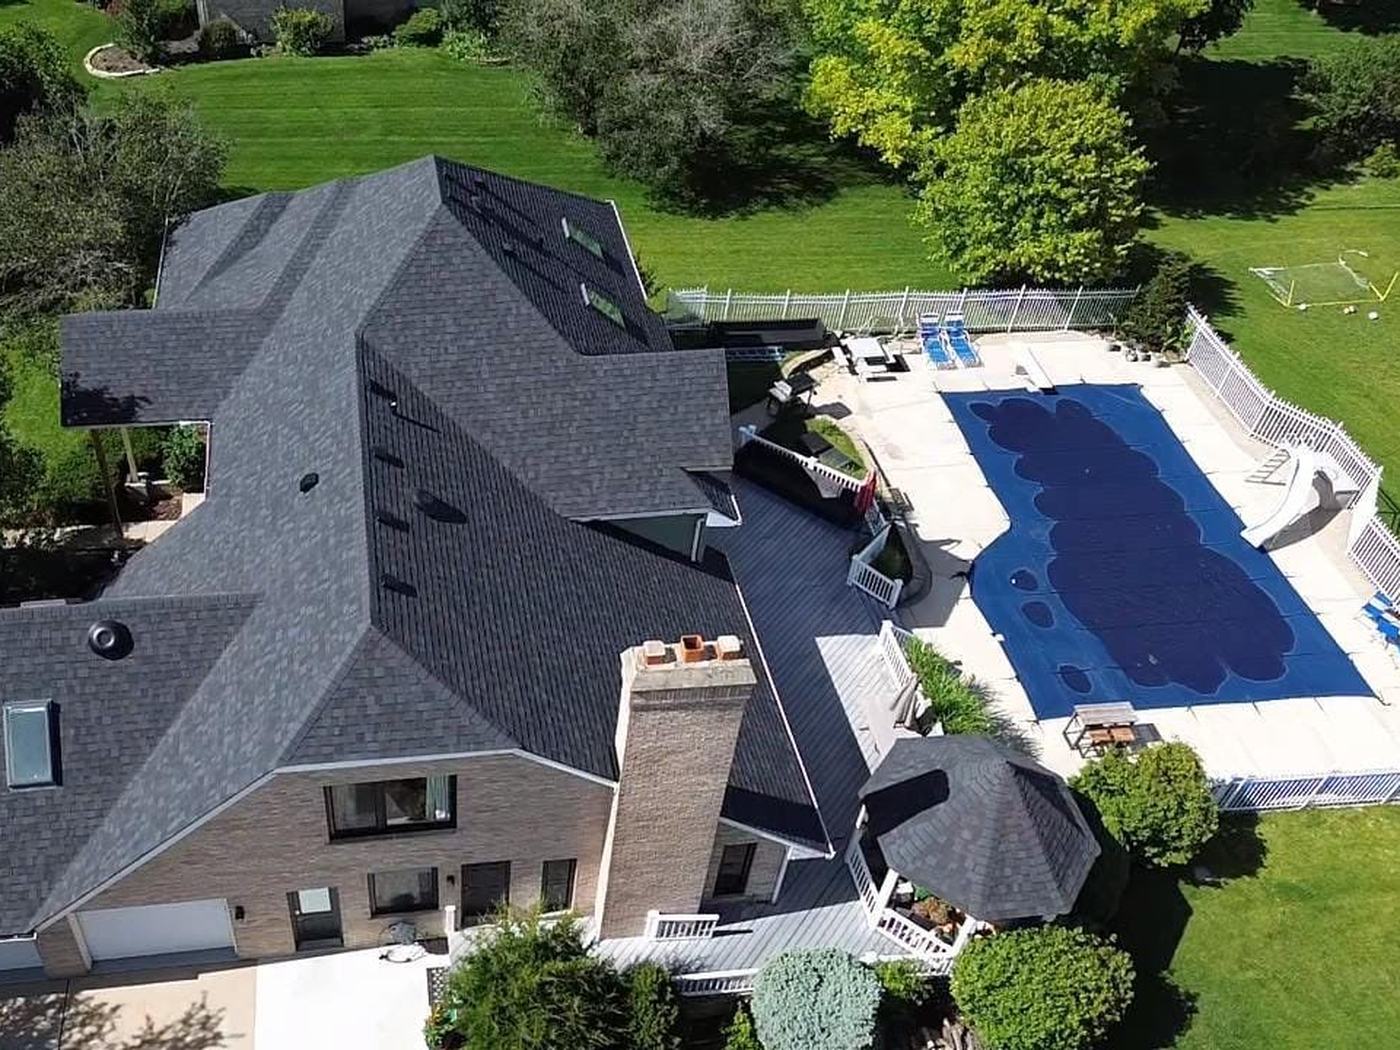
Drone view of a large brick home in New Lenox with a new dark roof, gazebo and pool
Trident job · New Lenox, IL · Roof
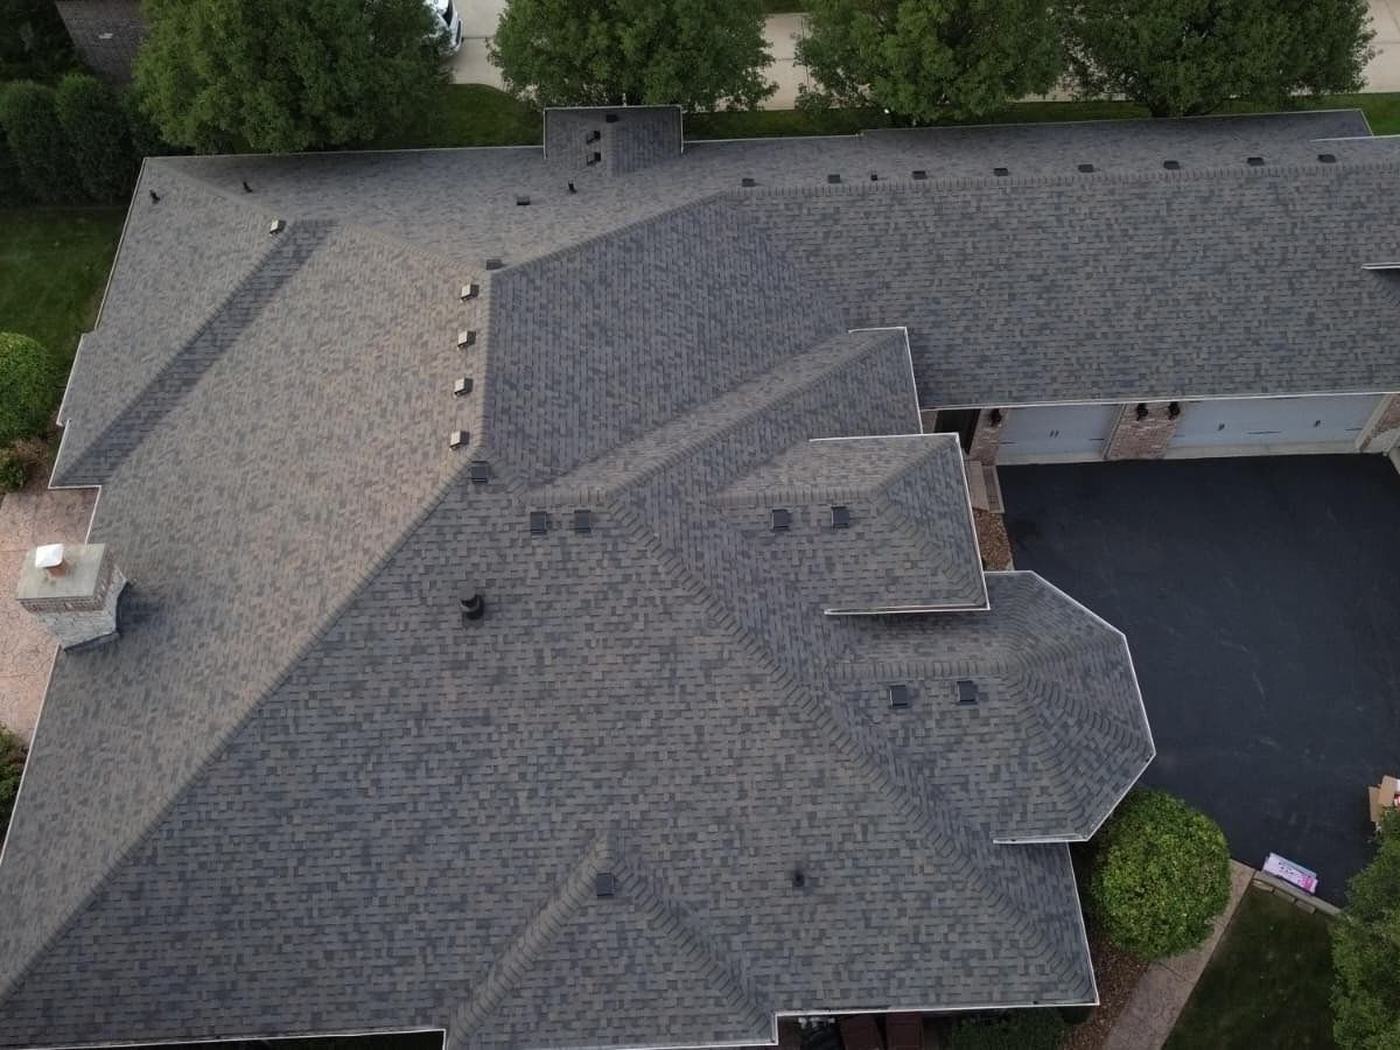
Drone view of a large ranch on a golf-course lot in Frankfort with a new gray roof
Trident job · Frankfort, IL · Roof
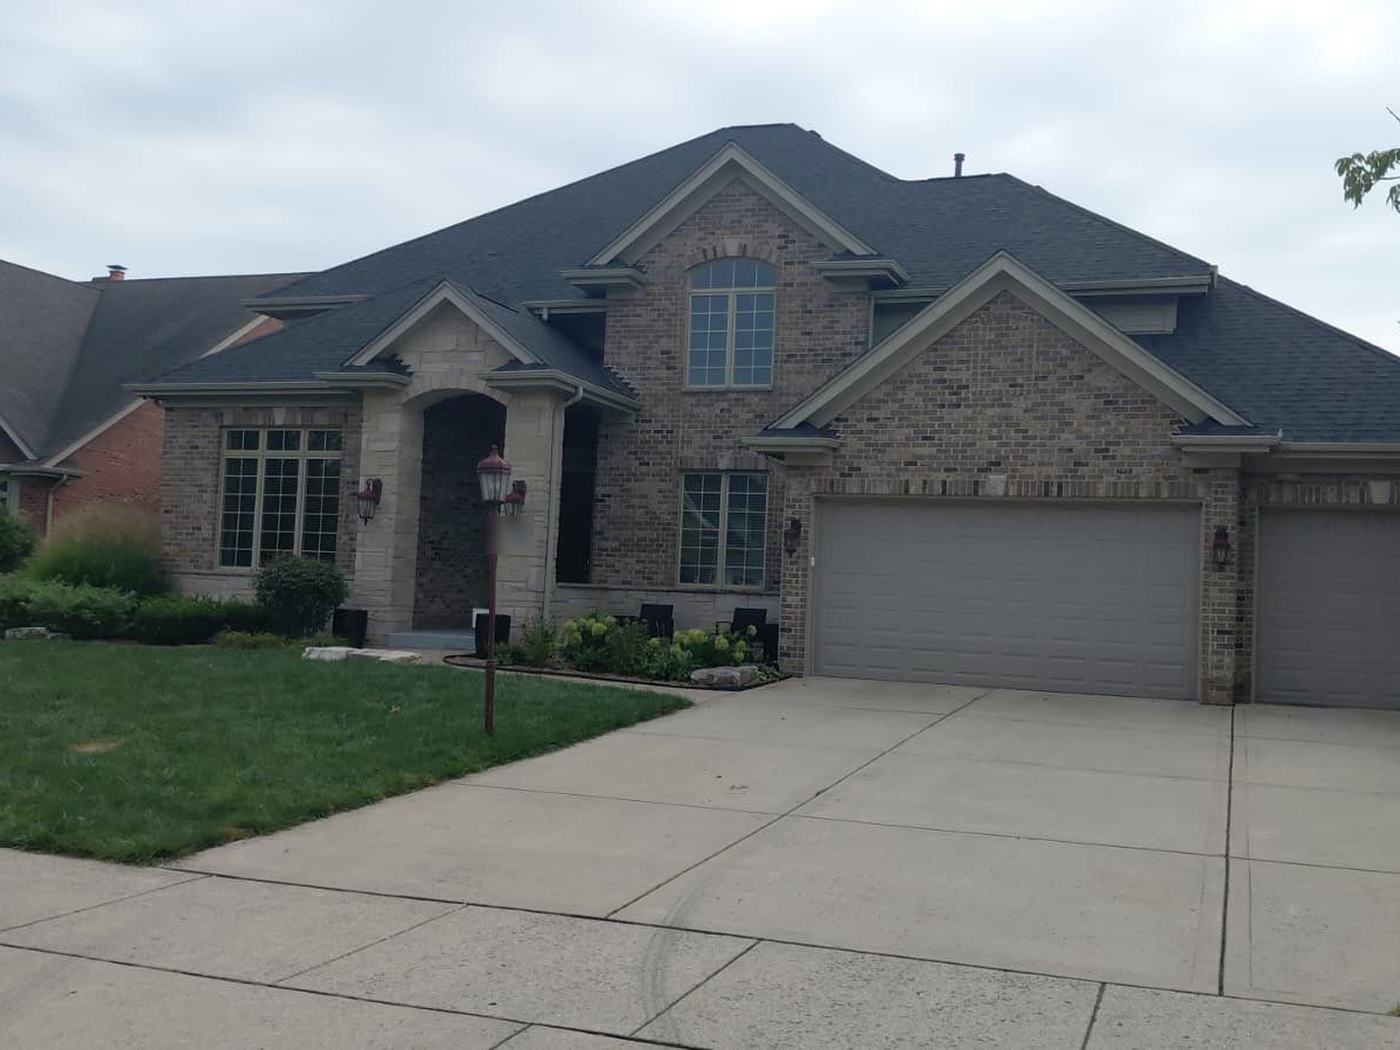
Brick two-story home in Munster with a new dark-gray roof and stone entry
Trident job · Munster, IN · Roof
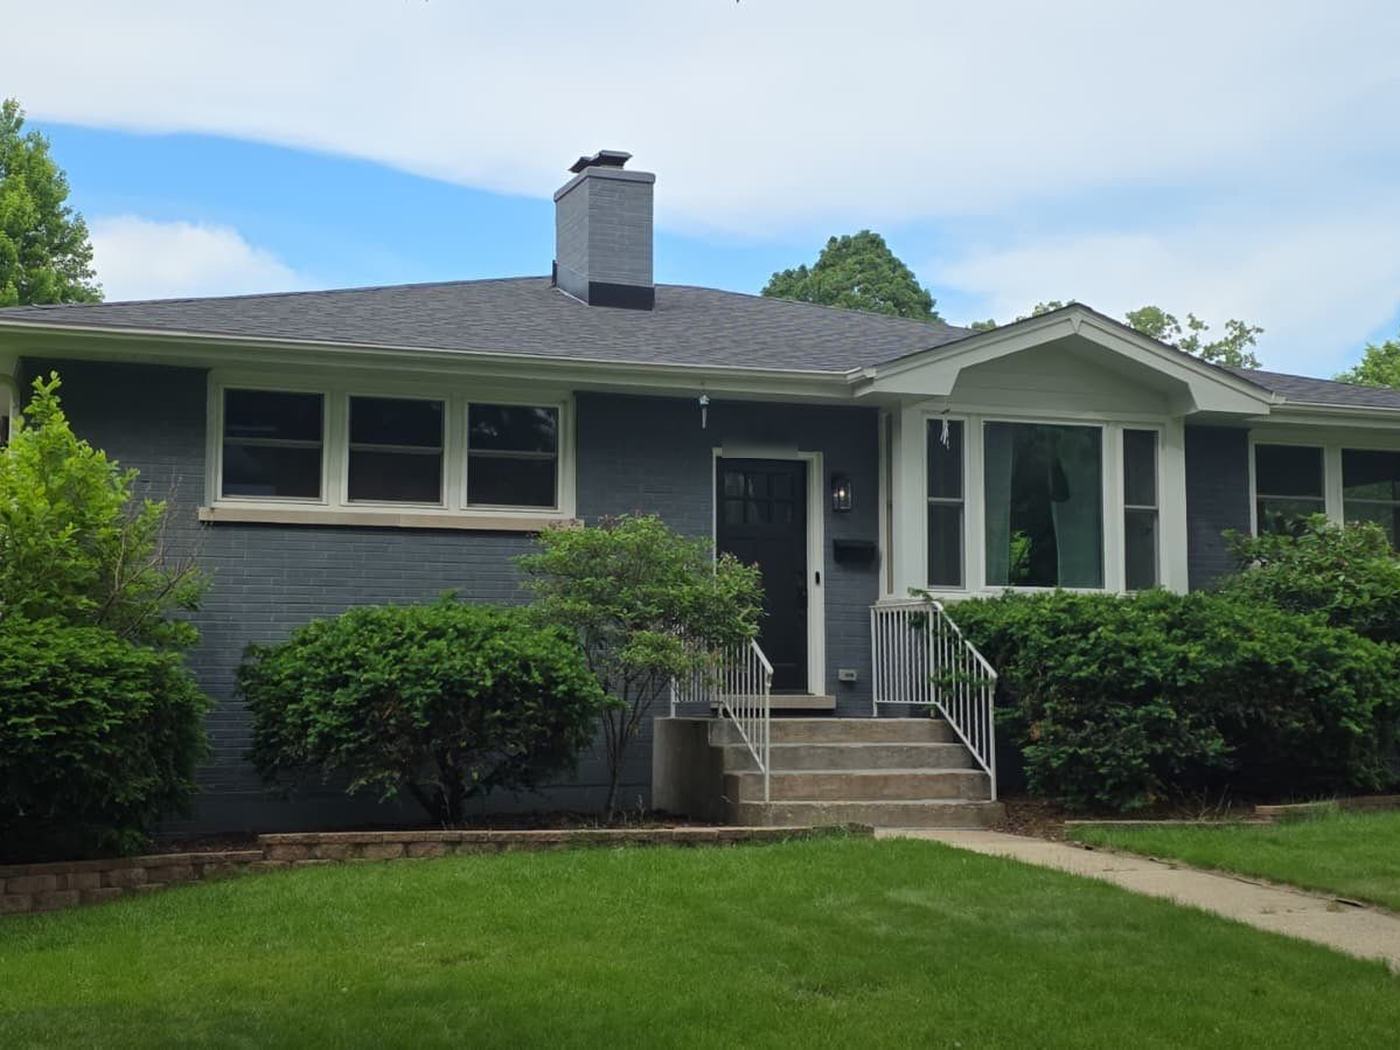
Gray brick ranch in Naperville with a new dark-gray roof
Trident job · Naperville, IL · Roof
Ranch home in the Dundee area with a new gray roof and flower beds
Trident job · Dundee area · Roof

"My insurance denied everything. Trident came out. Yes it took about 2 months but Allstate paid for everything!"

Ivan H. · Siding · HomeAdvisor

"Trident came by and told me my insurance owes for replacement and they made sure my insurance came back out."

Bill N. · Insurance claim · HomeAdvisor

"The communication from start to finish was stellar and they never missed a beat. The crew that came to install the new roof was courteous and cleaned up."

Penny L. · Roof & siding · HomeAdvisor

"Michael told me an insurance claim can take a long time but this was way faster. The project was top notch."

Joey P. · Metal siding · HomeAdvisor

"Michael and his staff were so professional. They were kind, and helped me get my roof approved by my homeowner's insurance."

Moe A. · Roofing · HomeAdvisor

"The entire Trident team was professional and efficient. My yard and lawn were left cleaner than they were before."

Peter W. · Siding · HomeAdvisor

08 Right after a storm

The first 48 hours decide the claim.

Four things to do before anyone touches the roof. Then text us the photos and we take it from there.

  1. 01

    Photograph everything

    Every side of the house, the roof from the ground, gutters, screens, the AC unit, anything dented. Wide shots and close-ups, before any cleanup.

  2. 02

    Stop the water, keep the receipts

    Tarp a leak or move furniture, but keep every receipt. Emergency protection is usually covered.

  3. 03

    Don't sign at the door

    Storm chasers show up within hours. Don't sign a contract or an assignment of benefits on the driveway. Get a second look first.

  4. 04

    Send us the photos

    Text them to (903) 952-2766 or start above. We'll tell you straight whether it's worth a claim.

09 Free guide

Document the claim right, and the carrier has nothing to argue with.

Most claims are lost in the first week, before anyone from the insurance company shows up. Our seven-step checklist walks you through what to do, in order, so the file is built before the adjuster arrives.

  • Get the date of loss rightThe one date the whole claim hangs on. How to find it, and what to say on the first call.
  • Photograph like an adjusterAll four sides, the roof from the ground, soft metals, granules in the gutters, timestamps on.
  • Tarp it, don't fix it yetProtect the house the same day, photograph before and after, and hold off on permanent repairs.
  • Save every receiptTarp, dry-out, hotel, tape. Plus a claim diary template for every call and every letter.
Free · 7 steps · printable

How to document a storm claim so it holds up

Checklist, claim diary, and what to ask the adjuster before they leave.

One email with the guide. After that, only when a storm hits your ZIP. Unsubscribe anytime.
Check your inbox. The checklist is on its way. You can also read it online now.

Prefer not to give an email? Read the guide online →

10 Questions

What people ask before they call.

Straight answers. If yours isn't here, call or text (903) 952-2766.

What does the inspection cost?

Nothing. We come out, photograph the roof, siding and gutters, and send you a written report with the photos. If nothing needs fixing, we tell you that.

What's a public adjuster, and why would I need one?

The adjuster the insurance company sends works for the insurance company. A public adjuster is licensed by the state to represent you, the policyholder. We document the loss, read the policy, price the damage line by line, and deal with the carrier so you don't have to.

My claim was denied or the offer seems low. Is it over?

No. A first offer is a starting point and a denial is a position. We reopen the file with new documentation, re-present it, and if the carrier won't move, most policies let each side name an appraiser to settle the amount under the policy's own appraisal provision.

What is appraisal, and does it mean I'm suing my insurance company?

No. Appraisal is a clause inside most policies for settling a disagreement about the amount of a covered loss, without a lawsuit. You name an appraiser, the carrier names one, the two pick an umpire, and any two of the three set the amount. It doesn't decide whether something is covered, only what the covered work is worth. We invoke it under your policy's own terms and walk you through every step. See how the panel works.

My letter says "covered" but they paid $0. Is that a denial?

Usually not. It means the carrier's estimate came in below your deductible. The damage is covered; the number is what's in dispute. Send us the letter and the estimate. If the scope is short, we re-measure, re-document and re-present it, and the payment often changes.

Can you cover my deductible?

No, and be careful of anyone who says they will. Your deductible is part of your policy. We never waive, rebate or absorb it.

How do the two Trident companies work together?

Simple: we adjust the loss and we work the construction. Trident Adjusting handles the claim with the carrier. Trident Construction does the build from the same photos and measurements. The terms are written into the agreement you sign, and we walk through them with you before you sign.

Who actually does the work?

Trident Construction Group Corp. is a general contractor. We manage the job, schedule the crews, order the material and photograph every stage so you can see exactly what went on your house.

What roofs do you build?

Architectural asphalt (IKO Cambridge and IKO Dynasty) over ice & water shield and synthetic underlayment. Commercial flat and low-slope roofs in TPO, EPDM and modified bitumen, including rooftop-unit curbs and drains. Metal roofing in standing seam, exposed-fastener panel and metal shingle. Designer systems: DaVinci composite slate and shake, cedar shake, clay tile, concrete tile and natural slate.

How long does a roof take?

Most single-family roofs are torn off and finished in one day. Siding runs longer depending on the house. You get photos of each stage as it goes.
11 Service area

Illinois and Indiana. Chicago suburbs to the Region.

Trident Adjusting is licensed as a public adjusting firm in both states, and our crews run both sides of the line. Don't see your town? Call or text (903) 952-2766 and we'll tell you if we cover it.

Illinois Chicago & the suburbs

  • Tinley Park
  • Orland Park
  • Orland Hills
  • Oak Lawn
  • Evergreen Park
  • Palos Heights
  • Burbank
  • Midlothian
  • Frankfort
  • Mokena
  • New Lenox
  • Homer Glen
  • Lockport
  • Joliet
  • Plainfield
  • Bolingbrook
  • Romeoville
  • Naperville
  • Lombard
  • Villa Park
  • Hinsdale
  • Justice
  • Berwyn
  • Northlake
  • Melrose Park
  • Des Plaines
  • Palatine
  • Lake Zurich
  • Bartlett
  • Carol Stream
  • Libertyville
  • Grayslake
  • Waukegan
  • McHenry
  • Dundee
  • Belvidere
  • University Park
  • Kankakee
  • Momence
  • Princeton
  • Chicago

Indiana Lake, Porter, Jasper, Newton & LaPorte counties

  • Merrillville
  • Munster
  • Griffith
  • Hobart
  • Portage
  • Chesterton
  • Porter
  • Burns Harbor
  • Cedar Lake
  • DeMotte
  • Lake Village
  • Valparaiso
  • Crown Point
  • Schererville
  • Highland
  • Hammond
  • Michigan City

Free, about a minute

Tell us what happened. We'll take it from there.

Five questions online, or one call. Either way you get a straight answer and a written report with photos.

Free guide + storm alerts

Know what your insurance letter really says.

Get the Letter Decoder: "covered," "ACV," "depreciation," "below deductible," in plain English, plus the five things to do before you sign anything. Then we'll only email you when a storm hits your ZIP.

One email now with the guide. After that, only when a storm hits your ZIP. Unsubscribe anytime.
Check your inbox. The Letter Decoder is on its way. If a storm hits your area, you'll hear from us first.